Financial
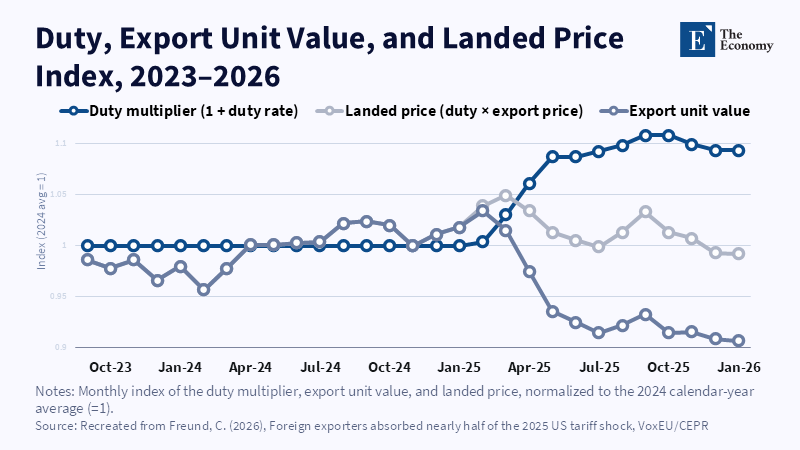
Export prices fell just as duties climbed, the two nearly canceling out at the border Related Articles: The Tariff Pass-Through Puzzle: Why Tariff Absorptio
Read More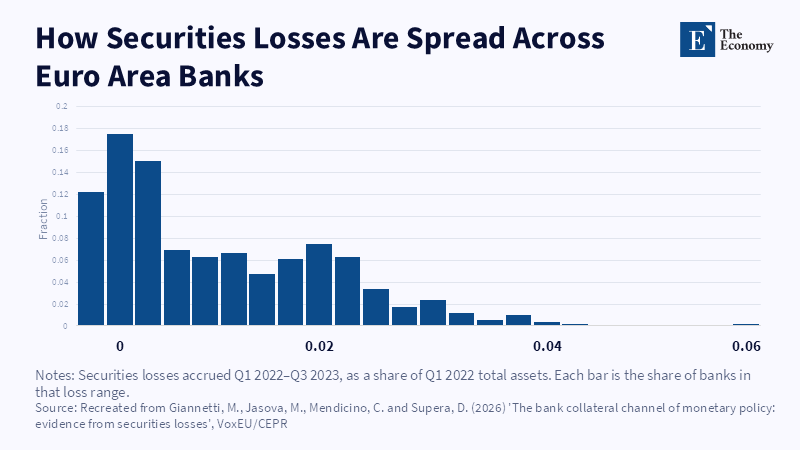
Most banks took modest losses, but a long tail of heavily exposed banks drove the pullback. Related Articles: The Collateral Channel Problem
Read More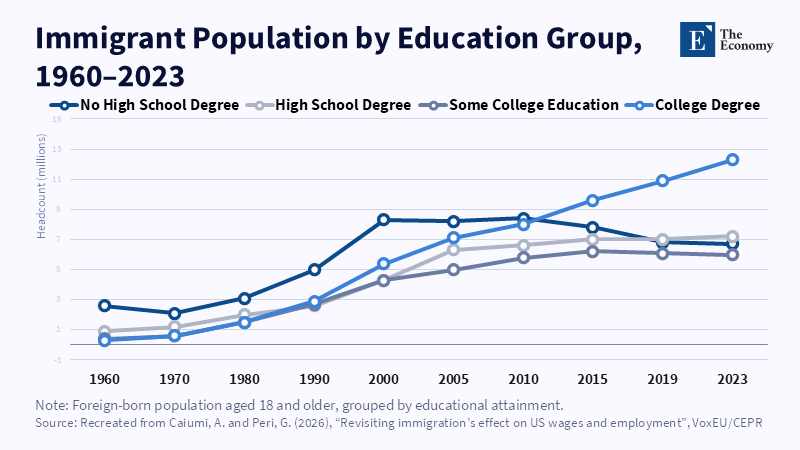
College-educated immigration expanded rapidly as growth among the least-educated reversed. Related Articles: Low-Skill Immigration Isn't the Wage Lever Was
Read More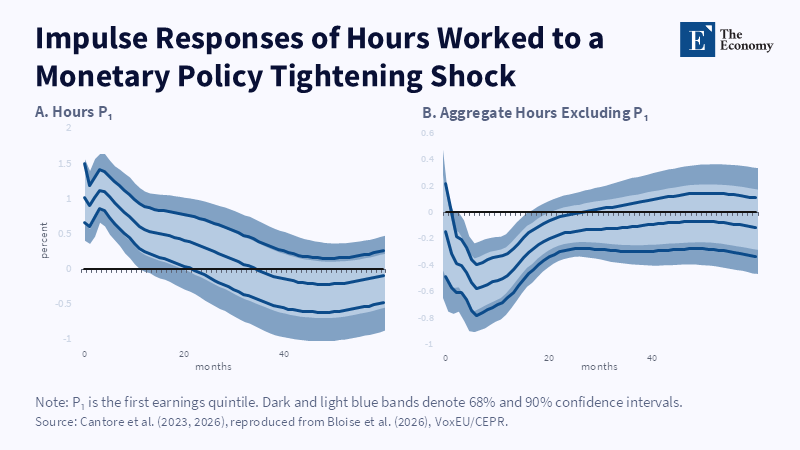
Lower-paid workers increase hours after tightening even as hours fall across the rest of the workforce. Related Articles: Labor Supply During
Read More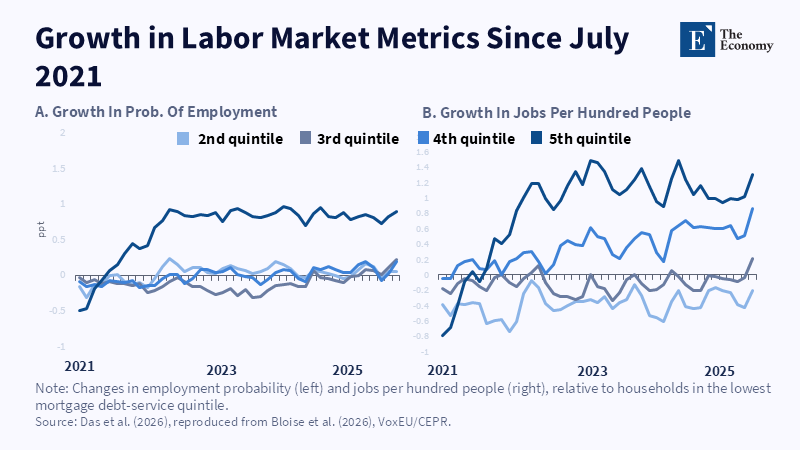
More mortgage-exposed households increased employment and took additional jobs as interest rates rose. Related Articles: Labor Supply Durin
Read More
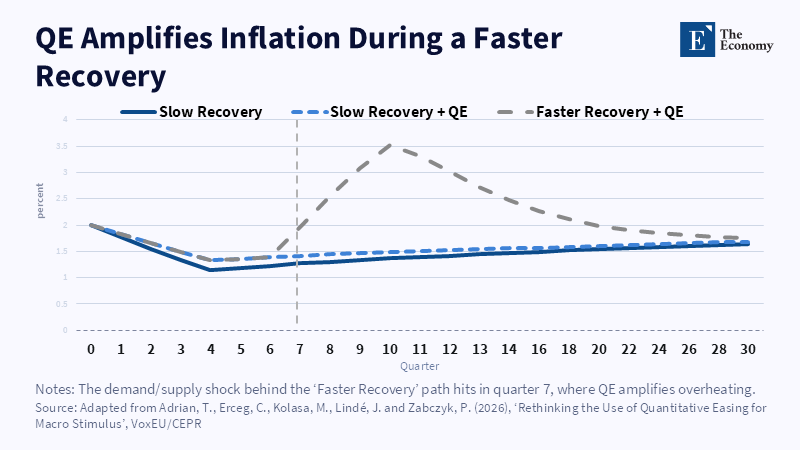
QE has little additional inflation effect during a slow recovery, but a faster rebound produces a sharp, temporary overshoot. Related Articles:
Read More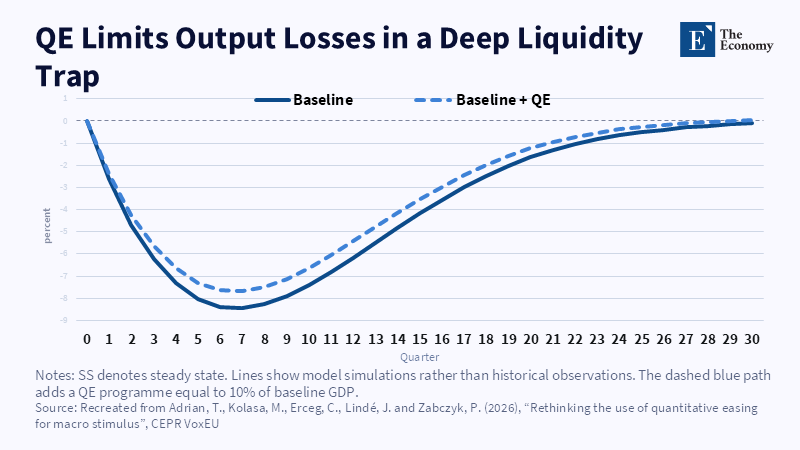
QE cushions the output decline in a deep liquidity trap, keeping output above the no-QE baseline throughout the recovery. Related Articles:
Read More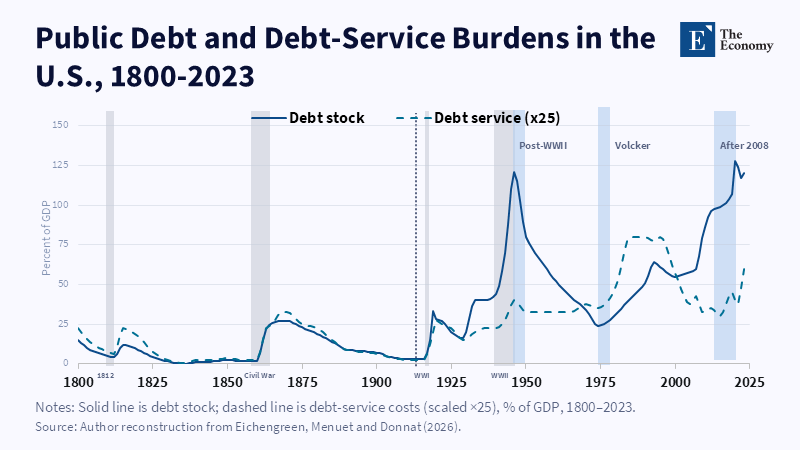
The lines split hard twice: debt soars after WWII while service costs barely move; service costs soar in the 1980s while debt stays flat. Related Articles:
Read More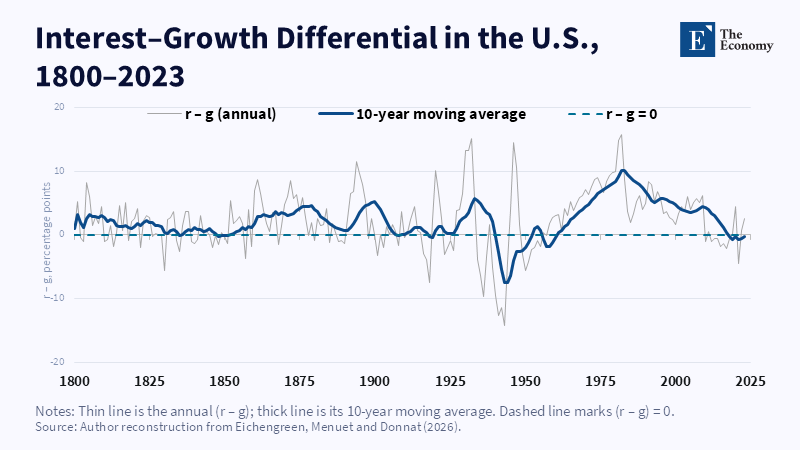
Every stretch above zero, especially the 1980s, lines up with real fiscal tightening.
Read More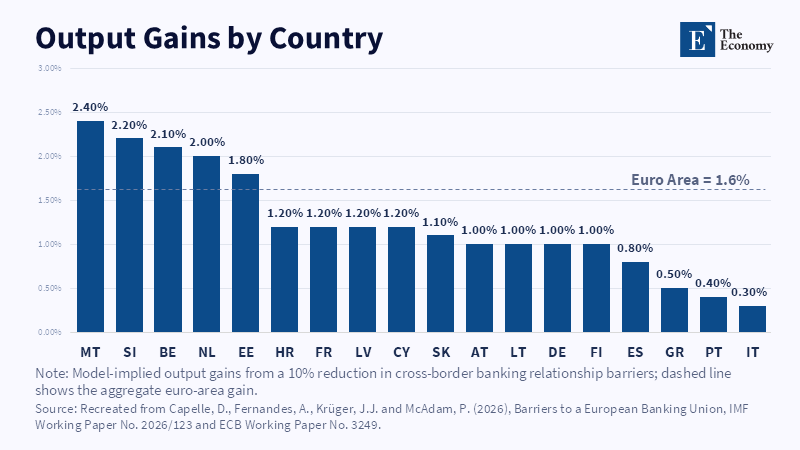
Lower cross-border banking barriers raise output across the euro area, although the gains vary sharply by country. Related Articles:
Read More
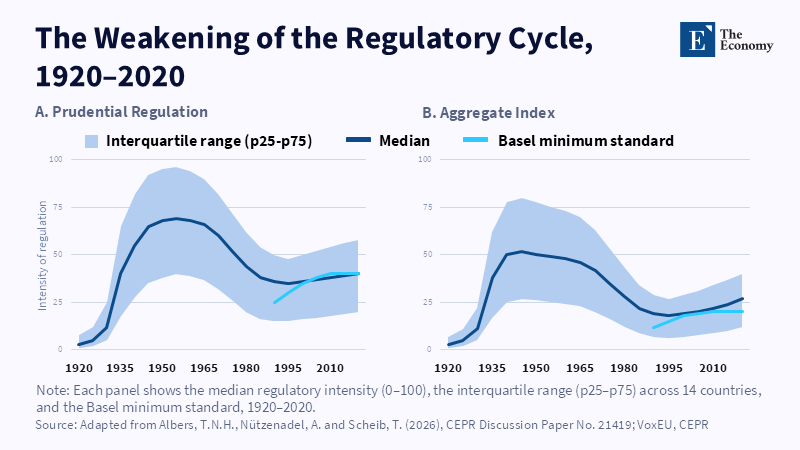
Regulation strengthened far less after 2008 than after earlier financial crises. Related Articles: When Euro Banks Fail: The Case for Cross-Border Banki
Read More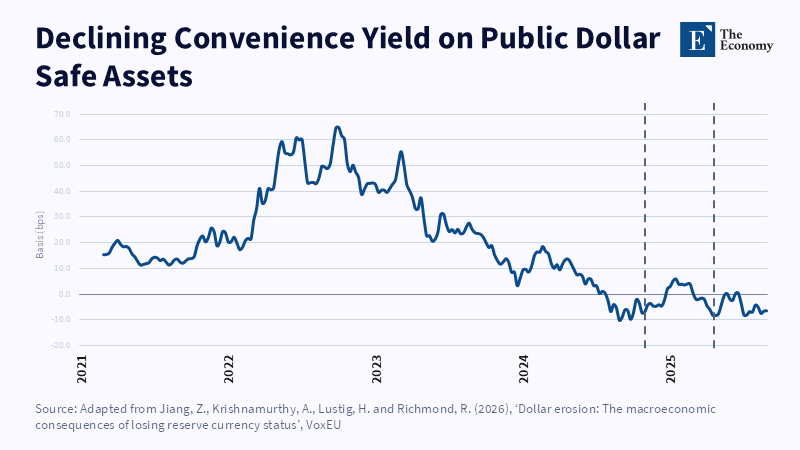
The convenience yield on US public safe assets has fallen sharply and remained near or below zero since late 2024. Related Articles: The Dolla
Read More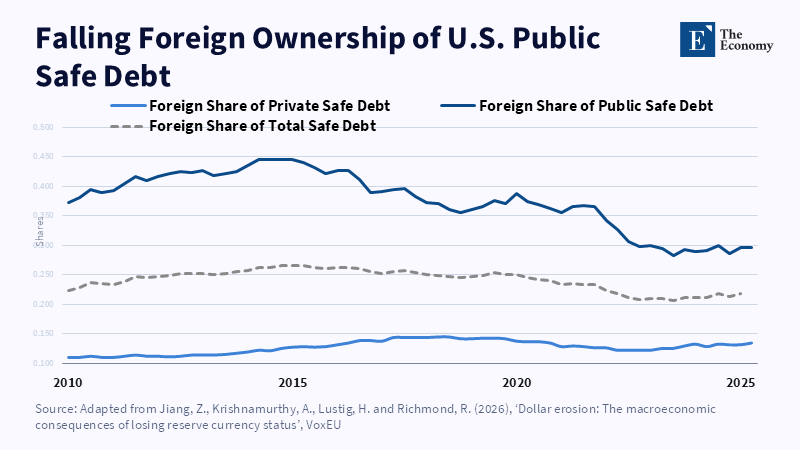
Foreign ownership of US public safe debt has fallen from roughly 45% to around 30%, while foreign ownership of private safe debt has remained broadly stable. Related Articles:
Read More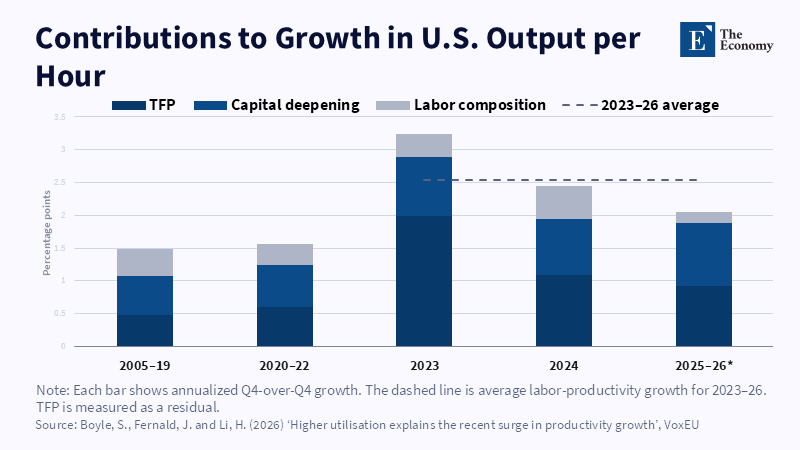
The post-2022 acceleration is concentrated in TFP, while capital deepening and labour composition contribute much less. Related Articles: The Cost Rese
Read More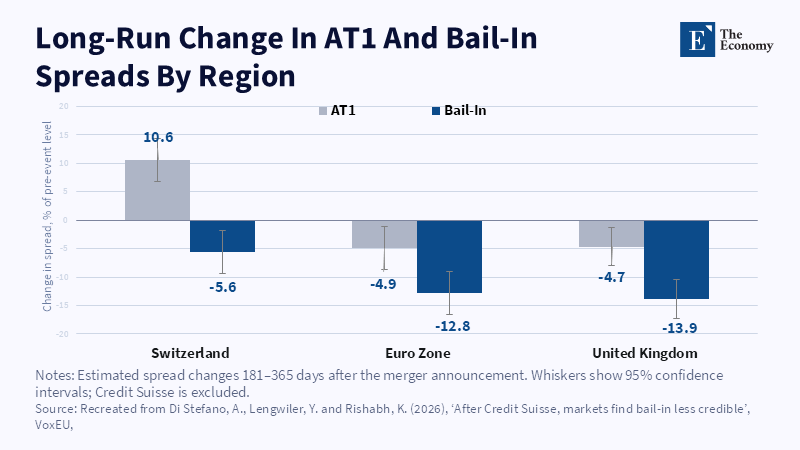
Bail-in spreads fell across all three regions, indicating that investors viewed future bail-in as less likely after Credit Suisse. Related Articles:
Read More
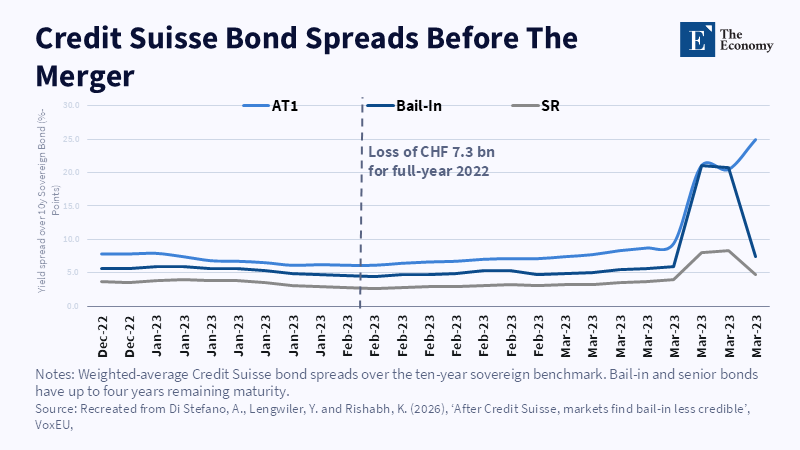
AT1 and bail-in spreads rose together before the merger, showing that investors expected both creditor layers to absorb losses. Related Articles: The
Read More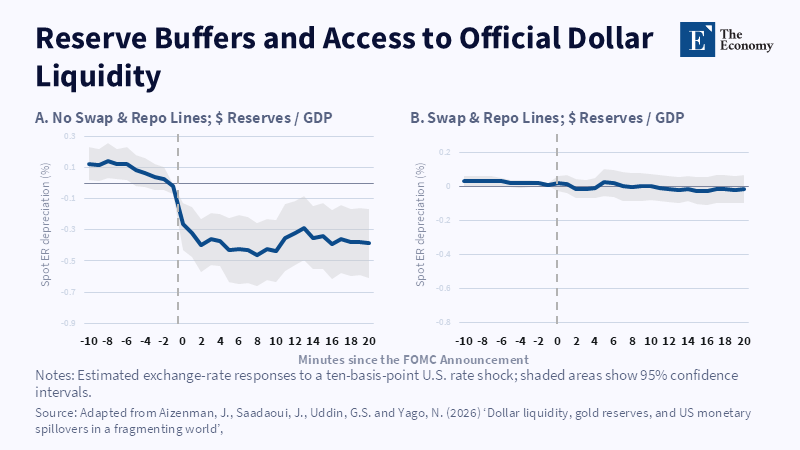
Note: Dollar reserves blunt Fed shocks mainly where countries lack official swap or repo access. Related article: Gold Cannot Stop a Dollar Run: Why Dollar S
Read More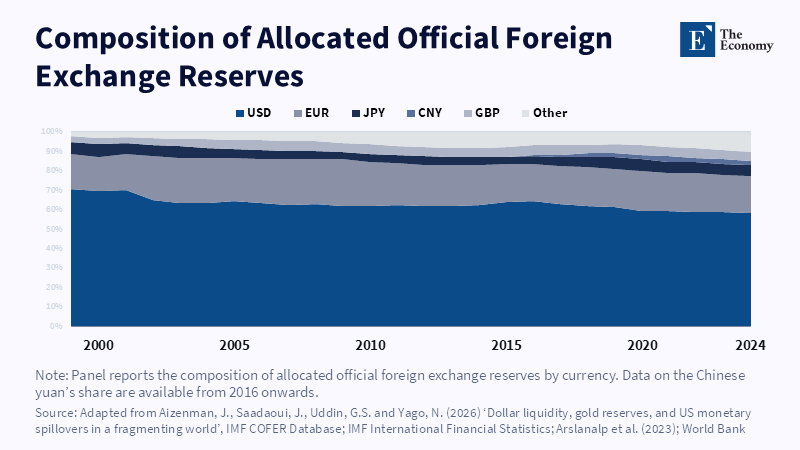
Note: The dollar still dominates official reserves, even as reserve managers diversify around the edges. Related article: Gold Cannot Stop a Dollar Run: Why D
Read More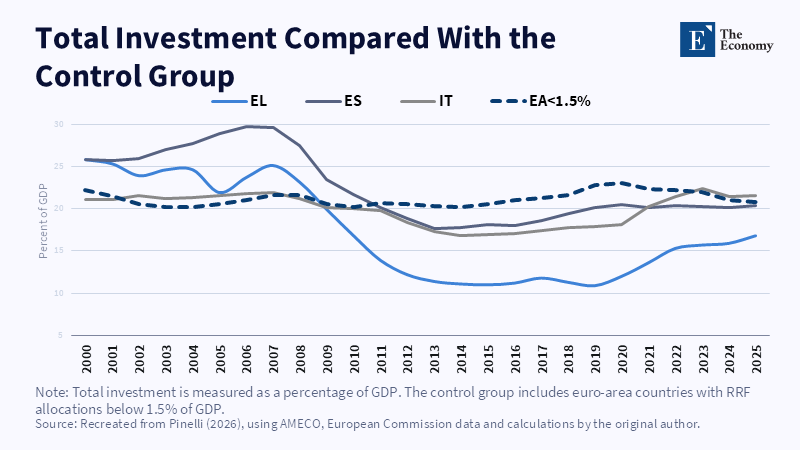
Note: Greece and Italy posted the largest rises in investment shares, while Spain’s increase was modest. Related article:
Read More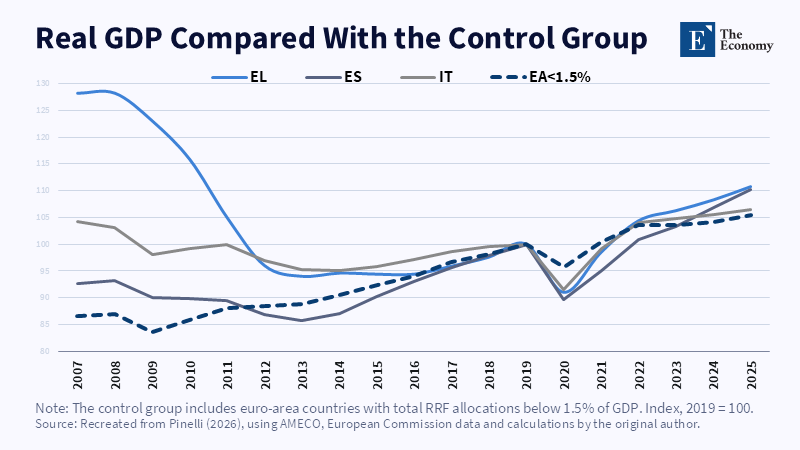
Note: Greece and Spain recorded the strongest output gains, while all three countries outperformed the low-allocation group. Related article:
Read More