Geopolitical Risk and Gold: Why Sanctions Are Reshaping Central Bank Reserves
The Economy Markets Editorial Board is a multidisciplinary group of researchers, analysts and sector specialists covering the structure and evolution of global professional and institutional markets. Its work examines competitive landscapes, market positioning, buyer choice and the forces reshaping industries across advisory services, capital markets, wealth management, healthcare and other specialist sectors.
The Board also contributes to The Economy’s ranking research, where its members assess firms, institutions and market participants using structured research, sector evidence and comparative analysis. This combination of market research and ranking coverage gives the Board a continuing view of how competitive positions develop within individual industries and how firms differentiate themselves as markets evolve.
Through The Economy Markets, the Board translates this research into accessible analysis of market structure, competitive dynamics and institutional change, complementing The Economy’s rankings, Wiki profiles and broader research coverage with a comparative view of the markets in which ranked organisations operate.
Authored on
Modified
Sanctions risk strengthens structural central-bank demand for gold
Less U.S.-aligned reserve managers show stronger gold accumulation
Gold diversification is increasing without replacing dollar dominance
At the end of 2025, gold now accounted for 27% of the world's total official reserves, surpassing the share of U.S. government bonds, which fell to 22%. A year earlier, the metal held only 20% of the total. The European Central Bank, which recorded the reversal in its latest report on the international role of the euro, attributed part of the change to the rise in the price of gold, but not all of it. Central banks continued to add physical gold to their reserves, not just watch their existing reserves become more expensive on their books. The dollar remains, in overall terms, the dominant unit of reserves, with a share of 42% when all dollar assets are factored in. The shift towards gold, however, is no longer marginal, and its cause is not only monetary. It is, to a large extent, geopolitical.
How Geopolitical Risk and Gold Demand Interact
For decades, U.S. government bonds have served as the indisputable benchmark for the concept of a safe asset: highly liquid, with negligible credit risk and easily liquid in crisis. But this financial security requires something that is often overlooked: these bonds are obligations issued under U.S. jurisdiction, so they are subject, at least in theory, to political interference. In 2022, when Washington and its allies froze much of Russia's foreign exchange reserves, this distinction ceased to be theoretical. What was considered non-negotiably safe turned out to be not equally safe for every holder.
Gold differs precisely on this point. It is not an obligation of any government, and when it is held outside the jurisdiction of a potential sanctioning state, it remains out of its reach. The price is known: zero return, custody costs, limited liquidity relative to a government bond. Gold is not a complete substitute for liquid safe assets, neither in theory nor in practice; it is an asset with a different combination of financial and geopolitical characteristics, and as the perceived potential for sanctions increases, the balance shifts towards it. A survey of a sample of 108 countries for the period 1990-2021 identified exactly this pattern: the increase in geopolitical risk is systematically linked to larger gold reserves, while the remaining foreign exchange reserves move more opportunistically according to immediate liquidity needs.
This distinction also changes the concept of security in a portfolio of foreign reserves. Credit quality and liquidity are no longer the only factors that matter when access to an asset may depend on relations with the issuing country. A government bond may remain financially secure but become politically less secure for a particular holder. Gold limits this exposure because it is not a sovereign obligation, although this advantage comes with costs in terms of yield and liquidity. The result is a more fragmented concept of a safe asset, in which the preferred form of reserve may vary according on geopolitical alignment.
A Portfolio Model of Sanctions Risk
The logic behind this shift can be articulated as a simple portfolio allocation problem. A reserve manager chooses how much of his portfolio to hold in sovereign bonds, denoted B, which yield interest i but are subject to sanctions risk, and how much in gold G, which yields zero yield but remains outside the range of a potential sanction when held outside of its jurisdiction. In a calm state of the world the probability of a penalty p is negligible and the liquidity advantage of the bonds dominates, so the reserve manager mainly holds B. In a turbulent situation, the expected yield of the bonds becomes (1−p)×i − p×L, where L represents the loss of access in the event of a sanction, and the expected yield drops as p rises, even before any sanction is imposed.
The result is a clear comparative static prediction: the share of gold in the optimal portfolio α increases with p, i.e. ∂α*/∂p > 0. This happens on two levels at once. In prices first: increased demand for gold puts upward pressure on its price, while reduced demand for bonds puts upward pressure on the yields that investors require to hold them. On the quantities, then: reserve managers not only see their existing gold become more expensive, but buy additional tons, which distinguishes a real portfolio realignment from a simple valuation phenomenon. The asymmetry is further reinforced for countries less geopolitically aligned with the United States, for which the perceived probability of sanctions already starts at a higher level.
Gold Takes a Larger Share of Official Reserves
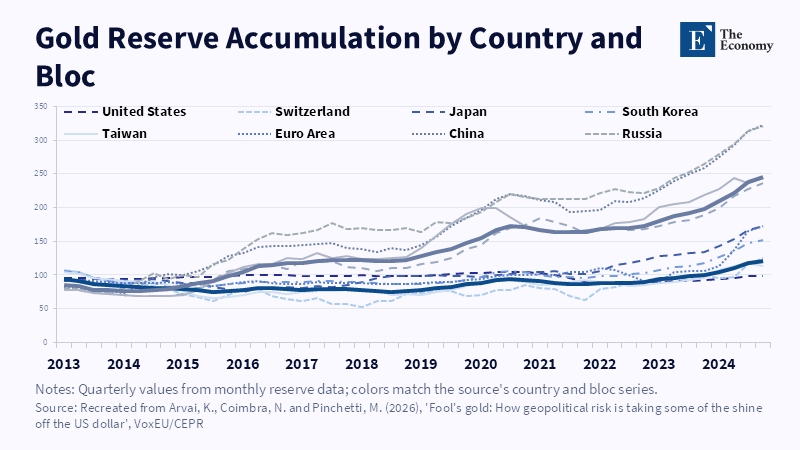
European Central Bank data give life to this pattern. At the end of 2025, gold had a 27% share of global official reserves, compared to 22% for U.S. government bonds and 15% for euro-denominated reserve assets. A year earlier, the ranking was different: 25% for bonds and just 20% for gold. The report itself warns against overestimating the reversal: if gold were valued at end-2023 prices, its share would approach 16%, with U.S. bonds remaining by far the largest single element of reserves.
But the increase is not only explained by the valuation. Central banks bought physical gold in large quantities after 2022, a period that coincided with the freezing of Russian reserves and the escalation of geopolitical tensions on multiple fronts. The dollar as a whole still holds the largest share of global reserves at 42%, which the ECB interprets as a sign of careful diversification rather than a sharp withdrawal from the dollar. The conclusion is not that gold is replacing the dollar as the dominant reserve currency, but that geopolitics has been added as a separate variable in reserve management, alongside traditional financial parameters.
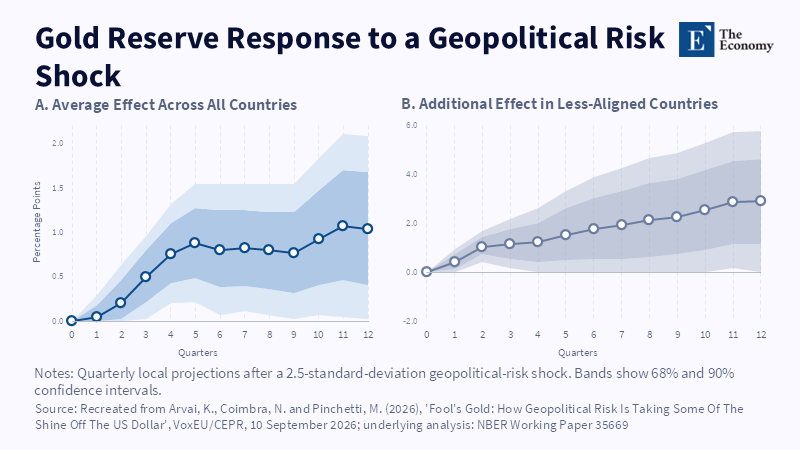
Table 1: Key Evidence on Geopolitical Risk and Official Gold Reserves
| Entity / Indicator | Role in the Mechanism | Latest Evidence | Market Implication |
|---|---|---|---|
| Geopolitical Risk Index (Caldara-Iacoviello) | Volume measurement | Reserve empirical model basis | Stable accumulation |
| People's Bank of China | Institutional Buyer | Over 80 tons in 2026 (Jan.-Aug.), 22 consecutive months of purchases | Stable accumulation |
| National Bank of Poland | Institutional Buyer | Largest single buyer in 2025 (102 tons) | Continued diversification |
| European Central Bank (report) | Recording of reserve composition | Gold share of 27% at the end of 2025 | Uptrend, not a full dollar replacement |
| World Gold Council | Industry research | Net purchases of 863 tons in 2025 | Positive outlook despite record prices |
Central Bank Gold Buying Remains Strong but Uneven
The buying trend can be clearly seen in the yearly figures. From 273 tonnes of net purchases in 2020, a year of low demand due to the pandemic, central banks switched to purchases of more than 1,000 tonnes per year in 2022, 2023 and 2024, before falling to 863 tonnes in 2025, when record prices forced several banks to become more selective in the timing of their purchases. Even this slowdown remains almost twice the average annual buying pace of 2010-2021, an indication that the shift towards gold has not reversed, it has simply acquired a more uneven pace.
Reserve managers also seem to view this shift as more than a temporary reaction to heightened geopolitical tensions. In the World Gold Council's 2026 survey, 89% of respondents expected global central bank gold reserves to increase over the next 12 months, while 45% expected their own institution to increase its holdings. At the same time, 83% expected gold to account for a larger proportion of total reserves over a five-year horizon. These expectations do not guarantee that purchases will continue at the same pace, especially when high prices can delay new allocations. But they show that gold is increasingly being seen as a strategic reserve allocation option rather than just a short-term reaction to isolated geopolitical episodes.
The People's Bank of China stands as the most emphatic example of institutional perseverance. In August 2026, the country's central bank completed 22 consecutive months of purchases, reaching approximately 2,387 tons in total, with the year's official purchases already exceeding 80 tons in the first eight months of 2026. The National Bank of Poland retained the title of the largest single buyer for the second year in a row in 2025, a period in which gold surpassed U.S. Treasuries as the largest single component of global reserves. Kazakhstan, Azerbaijan, and Brazil completed the list of 2025's major buyers, forming a market geography that extends far beyond countries in open rupture with Washington.
Sanctions against Russian and Iranian entities remain active; the war in Eastern Europe has not found a political solution, and the conflict around Iran has continued to disrupt markets into 2026: in August, new sanctions on Iranian-linked networks coincided with a new quarterly high for the price of the metal. China continues to build reserves at a steady pace, in line with its long-term ambition for greater monetary autonomy. None of these developments alone guarantee higher prices; the correction in the summer of 2026, when gold lost more than a quarter of its value relative to January's record, clearly demonstrated this. But as long as the question remains open as to which countries will be targeted by the next round of sanctions, central banks' monthly buying rates, not daily price fluctuations, remain the most reliable indicator to watch.
This article reflects the analytical judgment of The Economy Markets Editorial Board and does not constitute business advice or the official position of any affiliated institution.
References
Arslanalp, S., Eichengreen, B. and Simpson-Bell, C. (2023) ‘Gold as international reserves: A barbarous relic no more?’, Journal of International Economics, 145, 103822.
Arvai, K., Coimbra, N. and Pinchetti, M. (2026) ‘Fool’s gold: How geopolitical risk is taking some of the shine off the US dollar’, VoxEU/CEPR, 10 September.
Bailey, M.A., Strezhnev, A. and Voeten, E. (2017) ‘Estimating dynamic state preferences from United Nations voting data’, Journal of Conflict Resolution, 61(2), pp. 430–456.
Caldara, D. and Iacoviello, M. (2022) ‘Measuring geopolitical risk’, American Economic Review, 112(4), pp. 1194–1225.
European Central Bank (2026) The International Role of the Euro, June 2026. Frankfurt am Main: European Central Bank.
Ngo, V.M., Nguyen, P.V. and Hoang, Y.H. (2024) ‘The impacts of geopolitical risks on gold, oil and financial reserve management’, Resources Policy, 90, 104688.
World Gold Council (2026a) Central Bank Gold Reserves Survey 2026. London: World Gold Council.
World Gold Council (2026b) Gold Demand Trends: Q4 and Full Year 2025. London: World Gold Council.
World Gold Council (2026c) Gold Mid-Year Outlook 2026: Point Break. London: World Gold Council.
World Gold Council (2026d) ‘China gold market update: Official buying accelerated in August’, Goldhub, 14 September.
The Economy Markets Editorial Board is a multidisciplinary group of researchers, analysts and sector specialists covering the structure and evolution of global professional and institutional markets. Its work examines competitive landscapes, market positioning, buyer choice and the forces reshaping industries across advisory services, capital markets, wealth management, healthcare and other specialist sectors.
The Board also contributes to The Economy’s ranking research, where its members assess firms, institutions and market participants using structured research, sector evidence and comparative analysis. This combination of market research and ranking coverage gives the Board a continuing view of how competitive positions develop within individual industries and how firms differentiate themselves as markets evolve.
Through The Economy Markets, the Board translates this research into accessible analysis of market structure, competitive dynamics and institutional change, complementing The Economy’s rankings, Wiki profiles and broader research coverage with a comparative view of the markets in which ranked organisations operate.
Similar Post